Broker Check
Rated 5 out of 5 on Google

Certified Financial Planner In Wellington, FL. Coordinated Across Every Account.

Certified Financial Planners in Wellington, FL, working with equestrian estate owners, family businesses, and high-income households. Our financial planning covers non-liquid property cash flow, business succession, and multi-child education targets as a single plan.

  • Fiduciary CFP®
  • Fee-Based
  • 28 Miles To Boca Raton Office
  • 50-State Licensed
How A Financial Planning Relationship Works

The Wellington Family Planning Engagement

Discovery Meeting

The first meeting is a conversation, not a sales pitch. We map what you have, what you owe, what you're planning for, and where the real decisions are.

A Written Plan

You get a written plan you can actually follow. Cash flow, tax positioning, insurance review, retirement drawdown sequence, and estate hand-off, all in one document.

Quarterly Reviews

Meetings run on a real quarterly cadence, not once-a-year check-ins. The plan flexes as your life and the tax code change.

Certified Financial Planners

Our Certified Financial Planner is verifiable through the CFP Board directory. Required to put your interests first.

Fee-Based CFPs

Advisory work is fee-based and disclosed in writing before work begins. Where commissions apply (insurance, annuities), they're disclosed separately.

Licensed In All 50 States

The relationship continues if you move. Same advisor, same plan, from anywhere in the country.

Certified Financial Planners For Wellington Families

Our Fiduciary Certified Financial Planners For Wellington Families

Wellington concentrates high-income households across master-planned neighborhoods and the Equestrian Preserve Area, plus a growing base of medical and corporate professionals. The recurring reasons households here start looking for a financial advisor are non-liquid equestrian and land holdings, private business succession, and multi-child college funding alongside meaningful retirement targets.

Wellington counts roughly 61,600 residents with a median household income of $115,632, according to the US Census Bureau, and a meaningful share of household net worth here sits in non-liquid assets: equestrian facilities, acreage properties, and Palm Beach Polo real estate. That asset mix is why the planning work here focuses on building liquidity reserves that cover property taxes, insurance, and facility operations without forcing sales of growth equities during market downturns.
Key Planning Areas

Where Our Wellington Certified Financial Planners Focus

Equestrian Cash Flow

Equestrian operations have seasonal cash flow, operating costs, and property tax exposure. We size a dedicated liquidity pool so recurring costs never force a property or livestock sale.

Business Exit Planning

Private business owners often have a retirement plan tied to the business valuation at exit. We size a personal pool that stands on its own, with the exit as an accelerator.

Family Advisory Duty

A fiduciary recommends what fits the family plan, with every compensation source disclosed in writing before any work begins. That discipline matters more at higher wealth tiers.

529 And Retirement Balance

Multi-child households often face education targets in the same window as peak retirement accumulation. 529s, Florida Prepaid, and appreciated-asset gifting all fit specific situations.

Insurance For Land

Equestrian properties, agricultural holdings, and multi-property portfolios carry insurance exposure standard homeowner coverage doesn't address. We review coverage against the actual asset base.

Choosing A Fiduciary CFP

Households with equestrian operations, private business income, or multi-property portfolios need an advisor comfortable with the actual mechanics. First-call questions cover the rest.

Schedule Your Complimentary Consultation

No obligation. We respond the same business day.

I am Interested In
Approximate Household Income Range
Thank you! Your message has been received. Oops! Something went wrong. Please try again.
Related Services

The Full Wellington Family Planning Menu

What Our Fee-Based Financial Planners Don't Do

Contact Us Today

We don't lead with proprietary products, structured notes, or non-traded REITs as a portfolio building block. We don't take custody of your assets. We don't promise market-beating returns. The honest answer is that nobody who has to tell the truth to a regulator can.

ADDITIONAL INFO

Written Plan Delivery For Wellington Clients

suburban master-planned neighborhoods

Planning Mechanics For Non-Liquid Land And Estate Owners

Wellington is a community of 61,600 residents featuring suburban master-planned neighborhoods alongside a widely recognized Equestrian Preserve Area. The town maintains a median household income of $115,632, with meaningful wealth tied up in non-liquid real estate, equestrian facilities, and agricultural land.

In neighborhoods like Palm Beach Polo & Country Club, Aero Club, and Mallet Hill, financial planners evaluate liquidity ratios and seasonal cash flows. Real estate and equestrian holdings often involve substantial fixed expenses for property taxes, maintenance, and facility operations.

The CFP Board notes that financial planning for non-liquid asset owners must balance real estate value with liquid portfolio cash flows, ensuring the household maintains long-term financial flexibility.
financial planner in Wellington

How To Verify Credentials And Disciplinary Records

Selecting a financial planner in Wellington requires verifying credentials using public regulatory tools. Residents evaluating advisors should confirm whether an advisor holds the CERTIFIED FINANCIAL PLANNER mark and check their regulatory history through SEC and FINRA databases.

Investors can verify credentials through these official sources: CFP Board Verify a CFP Professional Tool, confirms current certification status and checks for public ethical disciplinary actions; SEC Investment Adviser Public Disclosure (IAPD), displays Form ADV filings, advisory fee disclosures, and regulatory histories for registered investment advisers; and FINRA BrokerCheck, provides background information, employment history, and customer dispute records for securities brokers.

Taking these verification steps confirms that Wellington families partner with an advisor who operates under strict ethical standards and maintains a clean regulatory history.
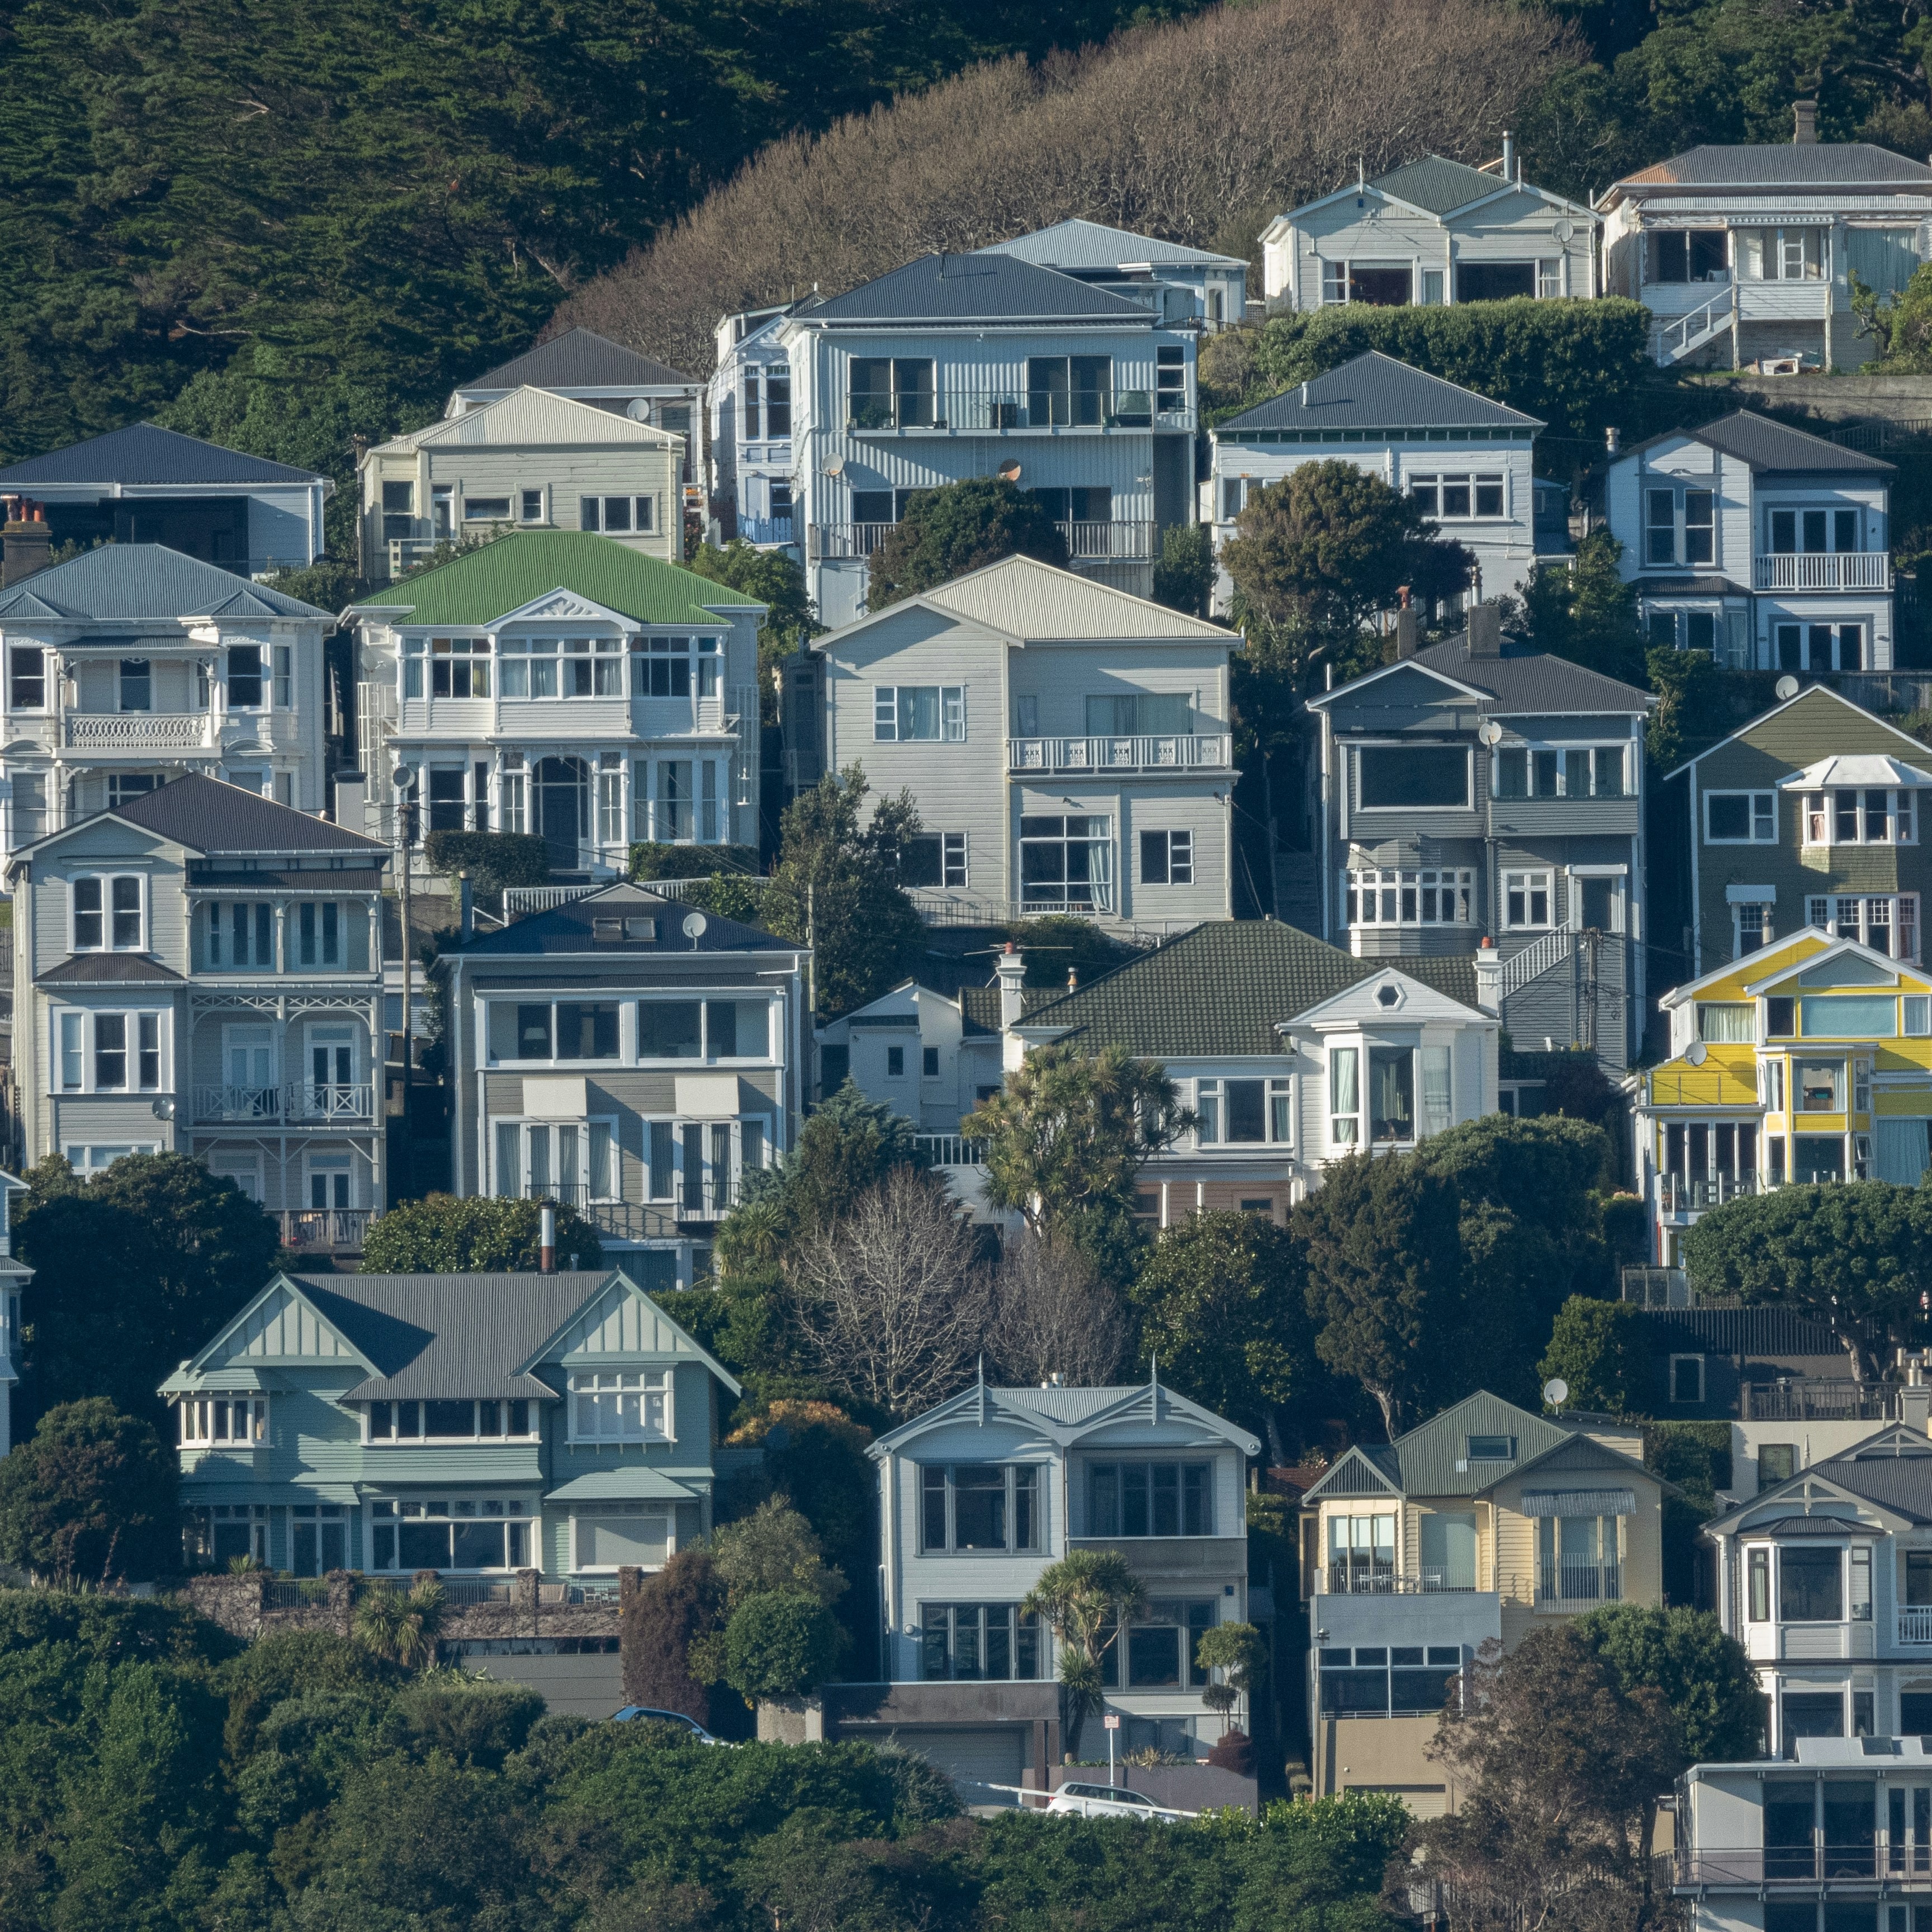
Suburban families in Wellington

Addressing Planning Gaps For Multi-Generational Households

Suburban families in Wellington master-planned communities like Olympia and Grand Coral handle competing financial goals, such as funding higher education through 529 plans while building pre-retirement savings. Without a structured financial plan, households can run into planning gaps, such as underfunding retirement accounts to cover short-term college costs or carrying improper liability insurance limits.

Common planning gaps for suburban families include: Education Vs Retirement Imbalance, overfunding 529 education accounts at the expense of workplace 401(k) or IRA catch-up contributions; Inadequate Umbrella Liability Coverage, maintaining baseline property insurance limits that fail to cover personal liability exposures for multi-property owners; and Uncoordinated Beneficiary Designations, neglecting to update retirement account and life insurance beneficiary forms after family expansions or marriages.

Working with an independent financial advisor helps households balance these priorities. By reviewing education targets, insurance limits, and retirement savings together, families establish a clear path toward long-term financial security.
RELATED READING

Read Our Insights on Financial Planning

Posts our planning team has put together on this topic.

Image for And the Executor Is

And the Executor Is

The right executor may help ensure the distribution of your assets is done with as little upheaval as possible.

Image for Financial Aid for Students 101

Financial Aid for Students 101

Help your college-bound child explore scholarships, grants, and more with this article on paying for higher education.
Image for FIRE Retirement

FIRE Retirement

This short, informative article teaches the basics of the FIRE movement.

Questions, Answered

Frequently Asked Questions

Self-management works for a simple paycheck plus 401(k). It gets expensive once you add Social Security sequencing, Roth conversion windows, equity-compensation vesting, estate planning, or a business sale. A CFP(R) ties the pieces together in one written plan and documents the trade-offs. For complex households, the plan typically saves more than the fee over a decade.

Yes, especially if the inheritance is over $250,000 or includes a mix of taxable, retirement, and real-estate assets. A CFP(R) builds the step-up basis review, inherited-IRA distribution schedule (10-year rule under SECURE Act), and estate-tax exposure into one written plan. Coordination with your estate attorney and CPA happens inside that plan.

Fiduciary duty means the planner must act in your interest at all times, disclose conflicts of interest in writing, use reasonable care and prudence, and document the rationale for each recommendation. It is a stricter standard than suitability. Every written plan from our firm is signed before any trade or filing moves, which locks the fiduciary record in place.

In Florida, flat annual advisory fees for households under $1M typically run $2,500 to $7,500 depending on complexity. Asset-based rates for households above $1M typically run 0.50% to 1.00% per year, tiered down as assets grow. Our rate schedule follows that range; the specific fee is written into the engagement memo before any plan work starts.

Yes. Florida's ag-classification (Greenbelt) status cuts assessed value substantially on bona fide agricultural use. For a Wellington horse farm, the plan documents the ag use (board, breed, train, show), coordinates the Palm Beach County Property Appraiser's annual review, and layers the estate structure (LLC or Family Limited Partnership) so the ag status survives the transfer. Your estate attorney handles the entity formation.

Seasonal equestrian income (concentrated January to April during the Winter Equestrian Festival) creates two cash-flow problems: cash reserves to carry the off-season, and quarterly estimated taxes against uneven income. The plan builds a 12-month cash-reserve rolling average, a SEP-IRA or Solo 401(k) that captures the peak-season income, and a Form 1040-ES schedule tied to actual quarterly earnings.

Our Boca Raton office serves Wellington households. The office is at 1200 N Federal Highway, Suite 300, Boca Raton, FL 33432. From Wellington, the drive is about 35 minutes southeast on Southern Boulevard and I-95. We meet in person at the office or virtually through our secure client portal, Monday through Friday, 8:30 AM to 4:30 PM ET.

Yes. Every Wellington engagement supports both in-person and virtual meetings through our secure client portal. Document review, screen share, and plan sign-off all work remotely. Many clients mix the two, starting in person for the discovery call and running quarterly reviews over video.

Ready to talk about Financial Planning?

The first meeting is a conversation, not a sales pitch. We'll talk about where you are, what you're working through, and whether Intercoastal is the right fit. In person in Boca Raton or Plantation, or by video from anywhere.

Schedule A Consultation