Broker Check
Rated 5 out of 5 on Google

Certified Financial Planner In Highland Beach, FL. Coordinated Across Every Account.

Certified Financial Planners in Highland Beach, FL. Focused on RMD sequencing, Medicare IRMAA management, and coastal-assessment liquidity reserves for retirees and coastal households.

  • Fiduciary CFP®
  • Fee-Based
  • 3 Miles To Boca Raton Office
  • 50-State Licensed
How A Financial Planning Relationship Works

What Highland Beach Retirement Planning Covers

Discovery Meeting

The first meeting is a conversation, not a sales pitch. We map what you have, what you owe, what you're planning for, and where the real decisions are.

A Written Plan

You get a written plan you can actually follow. Cash flow, tax positioning, insurance review, retirement drawdown sequence, and estate hand-off, all in one document.

Quarterly Reviews

Meetings run on a real quarterly cadence, not once-a-year check-ins. The plan flexes as your life and the tax code change.

Certified Financial Planners

Our Certified Financial Planner is verifiable through the CFP Board directory. Required to put your interests first.

Fee-Based CFPs

Advisory work is fee-based and disclosed in writing before work begins. Where commissions apply (insurance, annuities), they're disclosed separately.

Licensed In All 50 States

The relationship continues if you move. Same advisor, same plan, from anywhere in the country.

Highland Beach Residents

Our Fiduciary CFP Planning For Highland Beach Residents

Highland Beach is a coastal town of about 4,200 residents, a large share of them retired executives and second-home owners with meaningful investment accounts and coastal real estate. The recurring reasons households start looking for a financial advisor here are RMD sequencing, Medicare IRMAA management, and cash reserve planning against condominium special assessments.

Highland Beach counts roughly 4,200 residents across a three-mile stretch of A1A, and US Census Bureau data shows the town skews heavily to residents aged 65 and older living in owner-occupied properties. That demographic concentration is why the recurring planning work in this town centers on RMD sequencing, Medicare IRMAA management, and building assessment reserves that survive Florida's post-2021 structural integrity reserve requirements without forcing a sale of long-term holdings.
Key Planning Areas

Where Our Highland Beach Certified Financial Planners Focus

Managing RMD Strategies

RMDs push taxable income up in retirement. The IRA and 401(k) distribution order, plus any Qualified Charitable Distribution planning, materially affects the Medicare surcharge picture.

Coastal Condo Assessments

Coastal condo buildings face special assessments under Florida's Structural Integrity Reserve Study rules. We build the assessment risk into the cash flow model so a large hit doesn't disrupt the drawdown.

Dual-State Residency

Highland Beach residents often split time with a northern state. Documenting Florida residency, coordinating day-count records, and aligning account titling all affect the state-tax picture.

Insurance And Long-Term Care

Traditional LTC premiums have moved considerably. For substantial-asset households, self-insurance is often right. Middle-range households may fit a hybrid life-LTC product.

Estate Transitions

Beneficiary designations, account titling, and trust funding are where estate plans actually live. Attorneys draft the documents; we coordinate the funding and beneficiary audit.

Independent Advisor Model

Independent advisors aren't tied to a wirehouse product menu. That matters in retirement, when a captive-advisor annuity or insurance product can be difficult to unwind.

Schedule Your Complimentary Consultation

No obligation. We respond the same business day.

I am Interested In
Approximate Household Income Range
Thank you! Your message has been received. Oops! Something went wrong. Please try again.
Related Services

The Full Highland Beach Retirement Planning Menu

What Our Fee-Based Financial Planners Don't Do

Contact Us Today

We don't lead with proprietary products, structured notes, or non-traded REITs as a portfolio building block. We don't take custody of your assets. We don't promise market-beating returns. The honest answer is that nobody who has to tell the truth to a regulator can.

ADDITIONAL INFO

What Our Highland Beach Financial Planners Work Through

Financial Advisor In Oceanfront Communities

Choosing A Financial Advisor In Oceanfront Communities

Highland Beach stretches along three miles of Route A1A, representing a coastal town of approximately 4,200 residents dominated by oceanfront condominiums and private estates. Selecting a financial advisor in this market requires evaluating how an advisor addresses the needs of active retirees and dual-state property owners.

The US Census Bureau notes that Highland Beach features a high concentration of households aged 65 and older living in owner-occupied properties. In communities like Toscana and Bel Lido, retirees evaluating local advisors should look for professionals who coordinate closely with estate attorneys and tax specialists.

The Securities and Exchange Commission advises investors to ask prospective advisors whether they act as a fiduciary across all client accounts. Working with an independent registered investment adviser confirms that recommendations focus on long-term cash flow needs, asset location, and family governance goals.
Financial Planning Cadence For Retirees

The First-Year Financial Planning Cadence For Retirees

The initial year of a financial planning relationship establishes the operational framework for a household's retirement cash flow. In Highland Beach, the first-year engagement begins with a discovery process where the advisor gathers current account statements, tax returns, insurance policies, and estate documents.

During the second stage, the certified financial planner builds a written roadmap modeling probability-based retirement distributions. This model incorporates Social Security timing, pension choices, required minimum distributions, and cash buffers for property maintenance or condo assessments. The CFP Board emphasizes that a structured planning process must define measurable goals, evaluate potential risk factors, and present clear implementation steps.

Once the initial strategy is implemented, the advisor establishes a quarterly review cadence. In neighborhoods like Ocean Place and Villa Costa, these regular checkups allow the advisor and client to track withdrawal rates, adjust for tax law changes, and review cash reserves before major capital outlays occur.
Identifying Local Planning Gaps In Coastal Condos

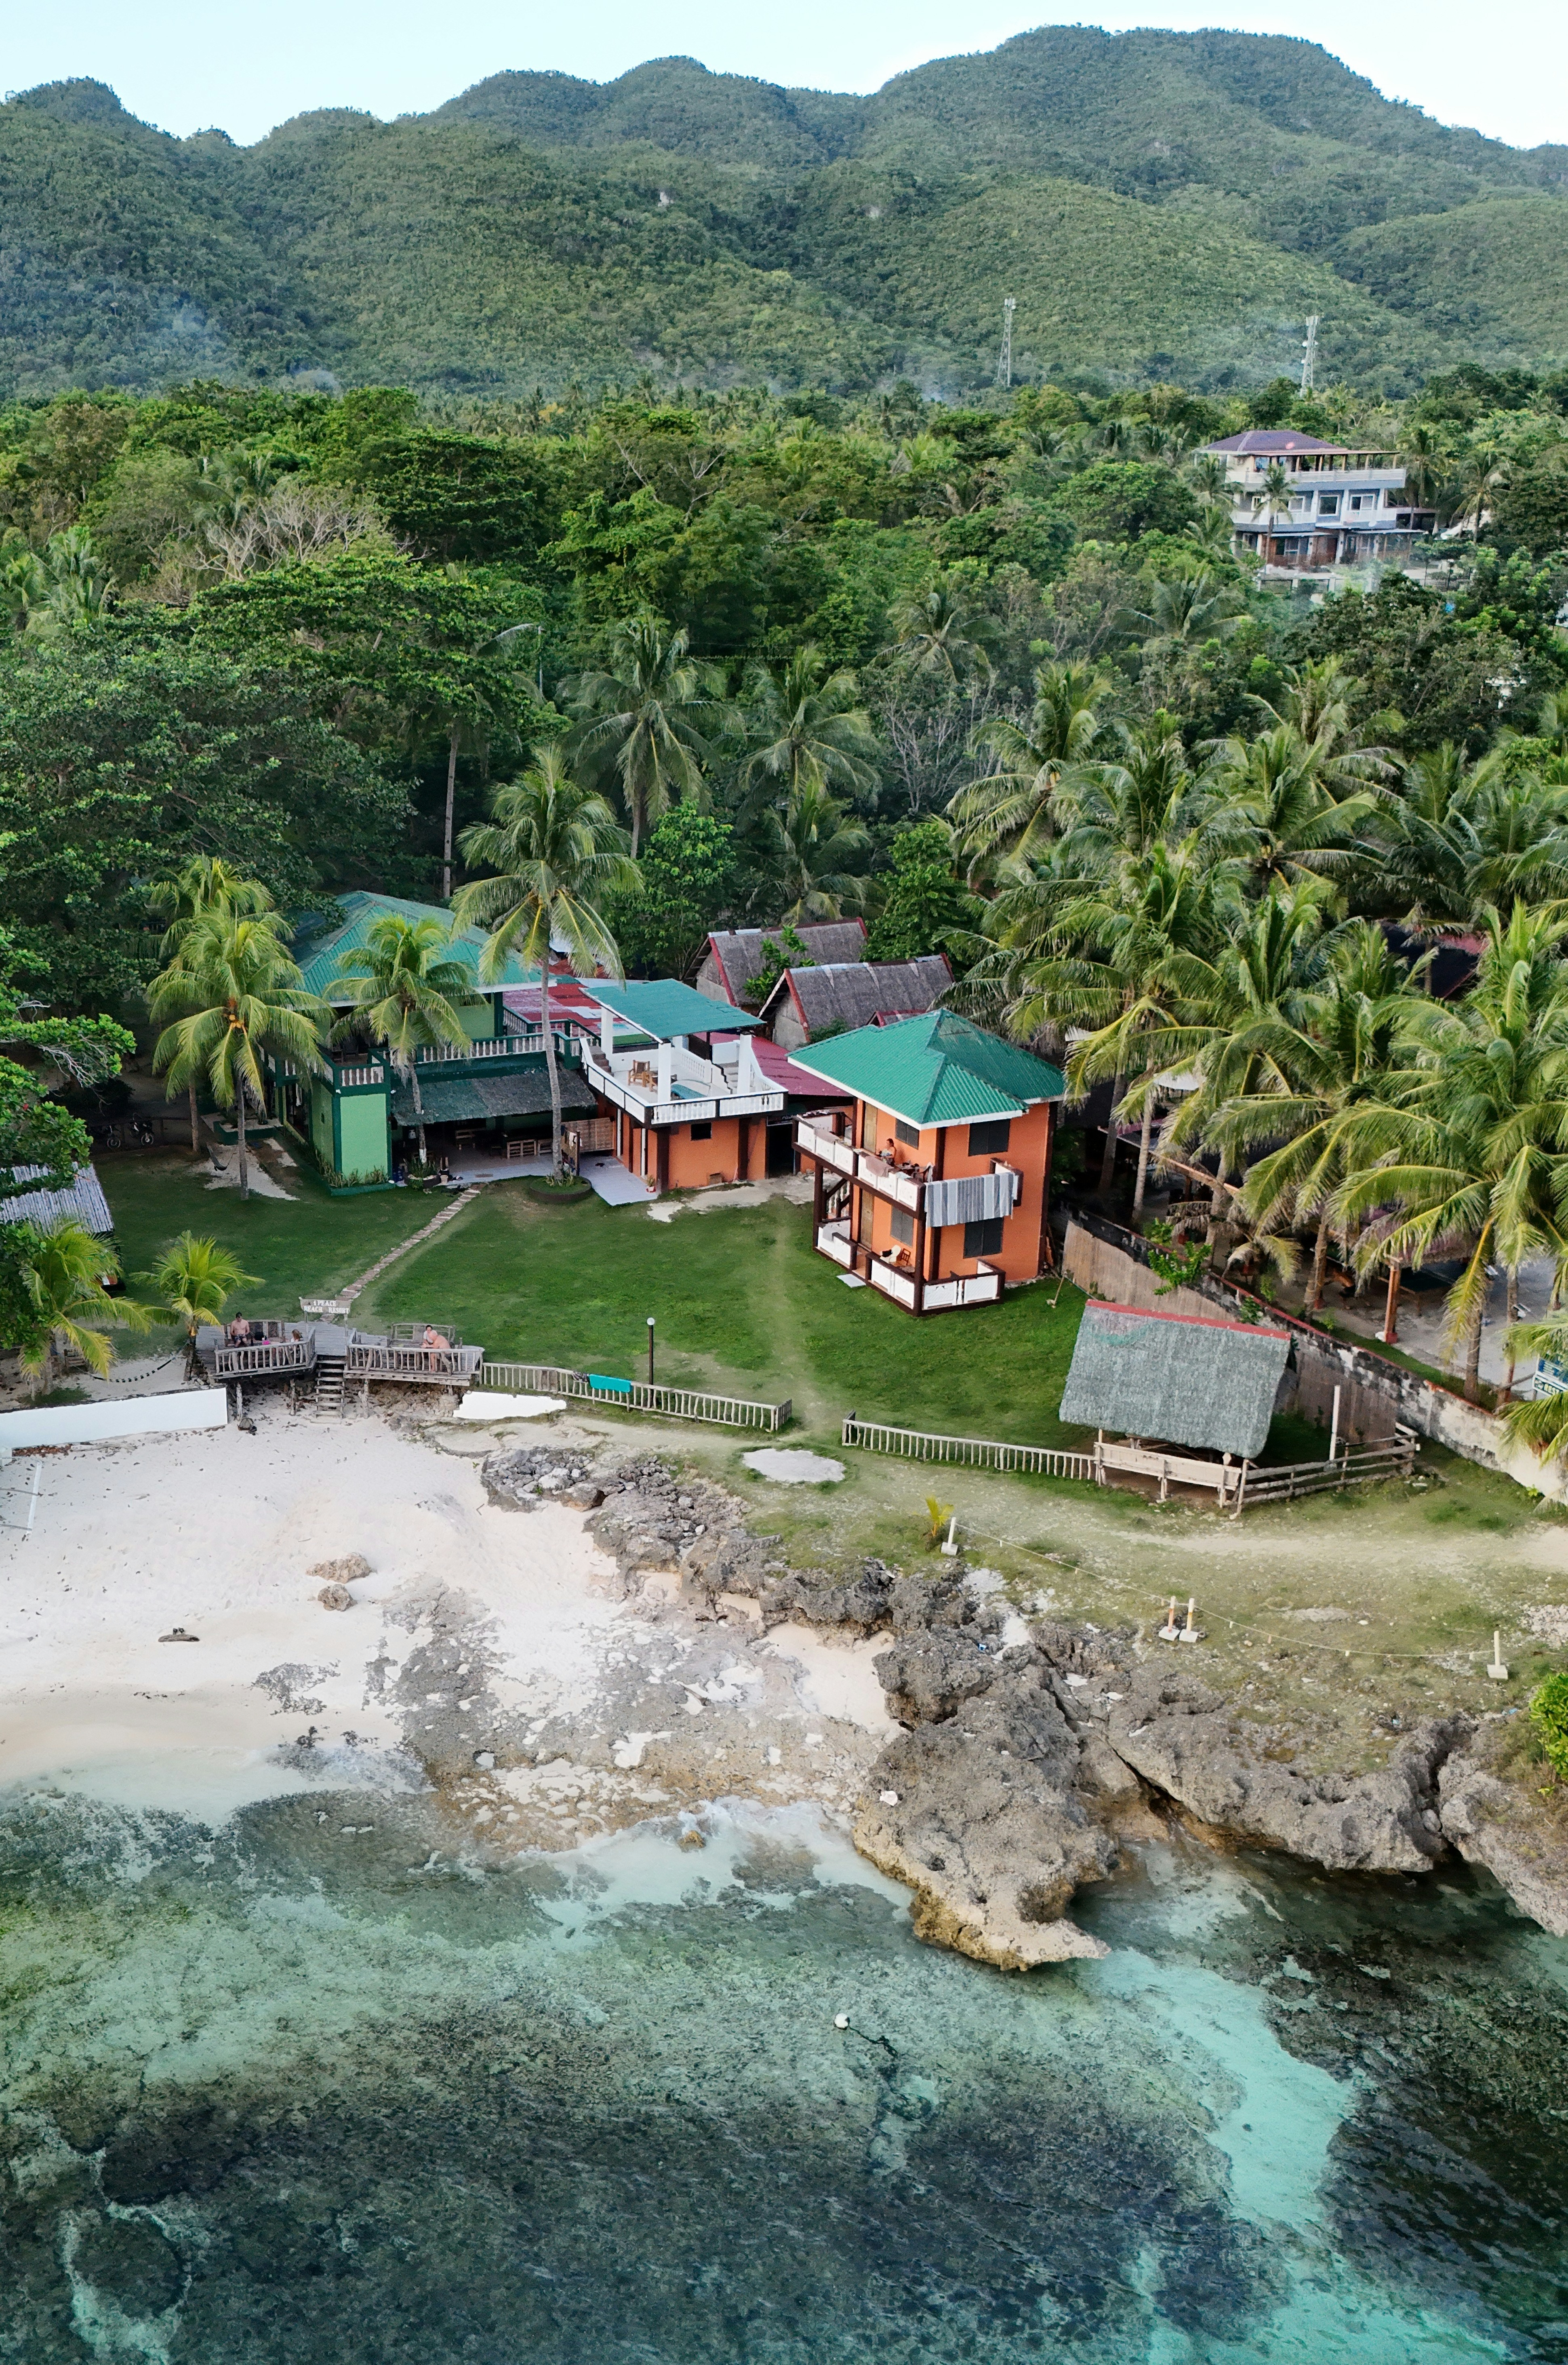
Retirees living in Highland Beach oceanfront condominiums face specific financial planning factors that are sometimes overlooked in generic retirement models. High-density coastal living involves ongoing homeowners association dues, potential special assessment risks from structural building reserve requirements, and rising property insurance costs. Incorporating these recurring and conditional expenses into a long-term cash flow model is important for maintaining household solvency.

The Florida Division of Condominiums, Timeshares, and Mobile Homes oversees regulations impacting condominium governance and financial reserve requirements across the state. Financial planning for Highland Beach condo owners includes pressure-testing cash reserves to handle HOA assessments without liquidating long-term growth equities during market downturns.

A personal trainer for money approach establishes dedicated liquid cash buckets alongside growth portfolios. By building assessment buffers and healthcare reserves directly into the initial plan, households along the Ocean Boulevard corridor can absorb property-related costs smoothly while keeping their long-term investment strategy on track.
RELATED READING

More From The Financial Planning Blog

Posts our planning team has put together on this topic.

Image for And the Executor Is

And the Executor Is

The right executor may help ensure the distribution of your assets is done with as little upheaval as possible.

Image for Financial Aid for Students 101

Financial Aid for Students 101

Help your college-bound child explore scholarships, grants, and more with this article on paying for higher education.
Image for FIRE Retirement

FIRE Retirement

This short, informative article teaches the basics of the FIRE movement.

Questions, Answered

Frequently Asked Questions

Four things: active CFP(R) certification verified at cfp.net, fiduciary status disclosed on Form ADV Part 2A, a written engagement scope with specific deliverables (plan, Investment Policy Statement, year-end tax memo), and transparent fee disclosure before the first meeting. Avoid firms that will not commit to all four in writing.

A CPA focuses on tax preparation, audit, and compliance filings. A CFP(R) focuses on the full household plan: cash flow, Investment Policy Statement, retirement income, risk management, and estate coordination. Tax strategy is one input in a CFP(R) engagement, not the primary deliverable. Many households keep both, with the CPA preparing annual returns and the CFP(R) building the plan the CPA plugs into.

Yes. The 10-year runway is when Social Security sequencing, Roth conversion windows, Medicare bracket planning, and healthcare-bridge planning get locked in. A CFP(R) builds the retirement income path by year, including which account to draw from first and how to avoid the IRMAA cliff. The plan is signed before any trade moves.

A CFP(R) can be registered with a broker-dealer and receive commissions on product sales, but during an advisory engagement the fiduciary standard still applies. Our firm's compensation is advisory fees billed to the household; brokerage execution is coordinated through J.W. Cole Financial where appropriate. All compensation sources are disclosed on Form ADV Part 2A.

An oceanfront Highland Beach condo typically carries significant appreciation and hurricane-insurance obligations. The plan compares three transfer paths: step-up basis at death (preserves full fair-market value for heirs), lifetime gift with retained use (triggers gift-tax reporting), and a qualified personal residence trust (QPRT). Coordination with your estate attorney starts before any deed is signed.

Yes. A Qualified Charitable Distribution (QCD) sends up to $105,000 per year (2024 limit, indexed) directly from the IRA to a qualified charity, satisfying the RMD without the amount hitting your 1040. For a Highland Beach retiree with charitable intent, the QCD lowers MAGI, which lowers IRMAA Medicare premiums and preserves ACA subsidy eligibility if applicable.

Our Boca Raton office serves Highland Beach households. The office is at 1200 N Federal Highway, Suite 300, Boca Raton, FL 33432. From Highland Beach, the drive is about 15 minutes south on A1A. We meet in person at the office or virtually through our secure client portal, Monday through Friday, 8:30 AM to 4:30 PM ET.

Yes. Every Highland Beach engagement supports both in-person and virtual meetings through our secure client portal. Document review, screen share, and plan sign-off all work remotely. Many clients mix the two, starting in person for the discovery call and running quarterly reviews over video.

Ready to talk about Financial Planning?

The first meeting is a conversation, not a sales pitch. We'll talk about where you are, what you're working through, and whether Intercoastal is the right fit. In person in Boca Raton or Plantation, or by video from anywhere.

Schedule A Consultation