Broker Check

Certified Financial Planner Coral Springs

Rated 5 out of 5 on Google

Certified Financial Planner In Coral Springs, FL. Built Around Your Whole Life.

Certified financial planners in Coral Springs, FL, working with mid-career professional families. Our financial planning covers systematic accumulation above the 401(k) match, 529 education funding, and family insurance coverage reviews.

  • Fiduciary CFP®
  • Fee-Based
  • 10 Miles To Plantation Office
  • 50-State Licensed
How A Financial Planning Relationship Works

What Coral Springs Family Planning Covers

Discovery Meeting

The first meeting is a conversation, not a sales pitch. We map what you have, what you owe, what you're planning for, and where the real decisions are.

A Written Plan

You get a written plan you can actually follow. Cash flow, tax positioning, insurance review, retirement drawdown sequence, and estate hand-off, all in one document.

Quarterly Reviews

Meetings run on a real quarterly cadence, not once-a-year check-ins. The plan flexes as your life and the tax code change.

Certified Financial Planners

Our Certified Financial Planner is verifiable through the CFP Board directory. Required to put your interests first.

Fee-Based CFPs

Advisory work is fee-based and disclosed in writing before work begins. Where commissions apply (insurance, annuities), they're disclosed separately.

Licensed In All 50 States

The relationship continues if you move. Same advisor, same plan, from anywhere in the country.

Certified Financial Planners For Coral Springs Families

Our Certified Financial Planners For Coral Springs Families

Coral Springs is a family-oriented city with a professional workforce across healthcare, education, and corporate management. The recurring reasons households here start looking for a financial advisor are mid-career cash flow allocation, 529 college funding balanced against retirement targets, and family insurance coverage reviews during peak earning years.

Coral Springs counts roughly 133,000 residents with a median household income near $90,000, per the US Census Bureau, and the city consistently ranks among Broward's senior public school districts, which drives long-tenure homeownership. That family-planning demographic is why the recurring planning conversation here centers on balancing 529 contributions against retirement catch-ups, structuring adequate own-occupation disability coverage on senior of group policies, and updating guardianship and beneficiary designations as kids age.
Key Planning Areas

Where Our Coral Springs Certified Financial Planners Focus

Mid-Career Accumulation

The 15-25-years-from-retirement window is where household wealth actually accumulates. Excess cash flow above the 401(k) match, HSA contributions, and Roth-versus-taxable decisions all move the needle.

College And Retirement Balance

529s, Florida Prepaid, and appreciated-asset gifting for tuition all fit specific situations. The education plan runs parallel to the retirement plan and should never push the retirement date.

Fiduciary CFP Guidance

A fiduciary is legally required to place the family's interests first. Every compensation source is disclosed in writing. The recommendation fits the plan, not the highest commission.

Family Insurance Gaps

Group life and disability coverage typically caps below the household's actual replacement need. Single-earner or dual-income households often carry a real gap worth checking.

Mortgage Vs. Investing

Accelerated payoff versus taxable-account investing is a specific math problem based on the mortgage rate, tax bracket, and expected portfolio return. We model both paths first.

Choosing A Fiduciary CFP

First-call questions: Are you a fiduciary? Do you hold the CFP®? How are you compensated, in writing? Those three cover the essentials for a growing family in Coral Springs.

Related Services

Every Coral Springs Family Planning Service

What Our Fee-Based Financial Planners Don't Do.

Contact Us Today

We don't lead with proprietary products, structured notes, or non-traded REITs as a portfolio building block. We don't take custody of your assets. We don't promise market-beating returns. The honest answer is that nobody who has to tell the truth to a regulator can.

ADDITIONAL INFO

Financial Planning Mechanics For Coral Springs Households

Coral Spring house

The First Meeting Discovery Process For Mid-Career Families

Coral Springs is a planned family community in northwestern Broward County, home to over 133,000 residents and a median household income of approximately $90,000. The local workforce includes healthcare professionals, corporate managers, educators, and small business owners raising families. For mid-career households, the initial financial planning meeting is designed as an open, educational conversation rather than a sales presentation.

During the discovery meeting, a certified financial planner reviews your household's full financial picture: Cash Flow and Expense Audits (reviewing monthly savings rates, mortgage terms, and family living expenses); Retirement Accumulation Accounts (examining workplace 401(k) selections, 403(b) allocations, and individual IRAs); and Family Protection and Education Goals (evaluating 529 college savings accounts, life insurance policies, and disability coverage).

The CFP Board emphasizes that a thorough discovery process helps advisors construct personalized plans that address immediate household needs while maintaining progress toward retirement.
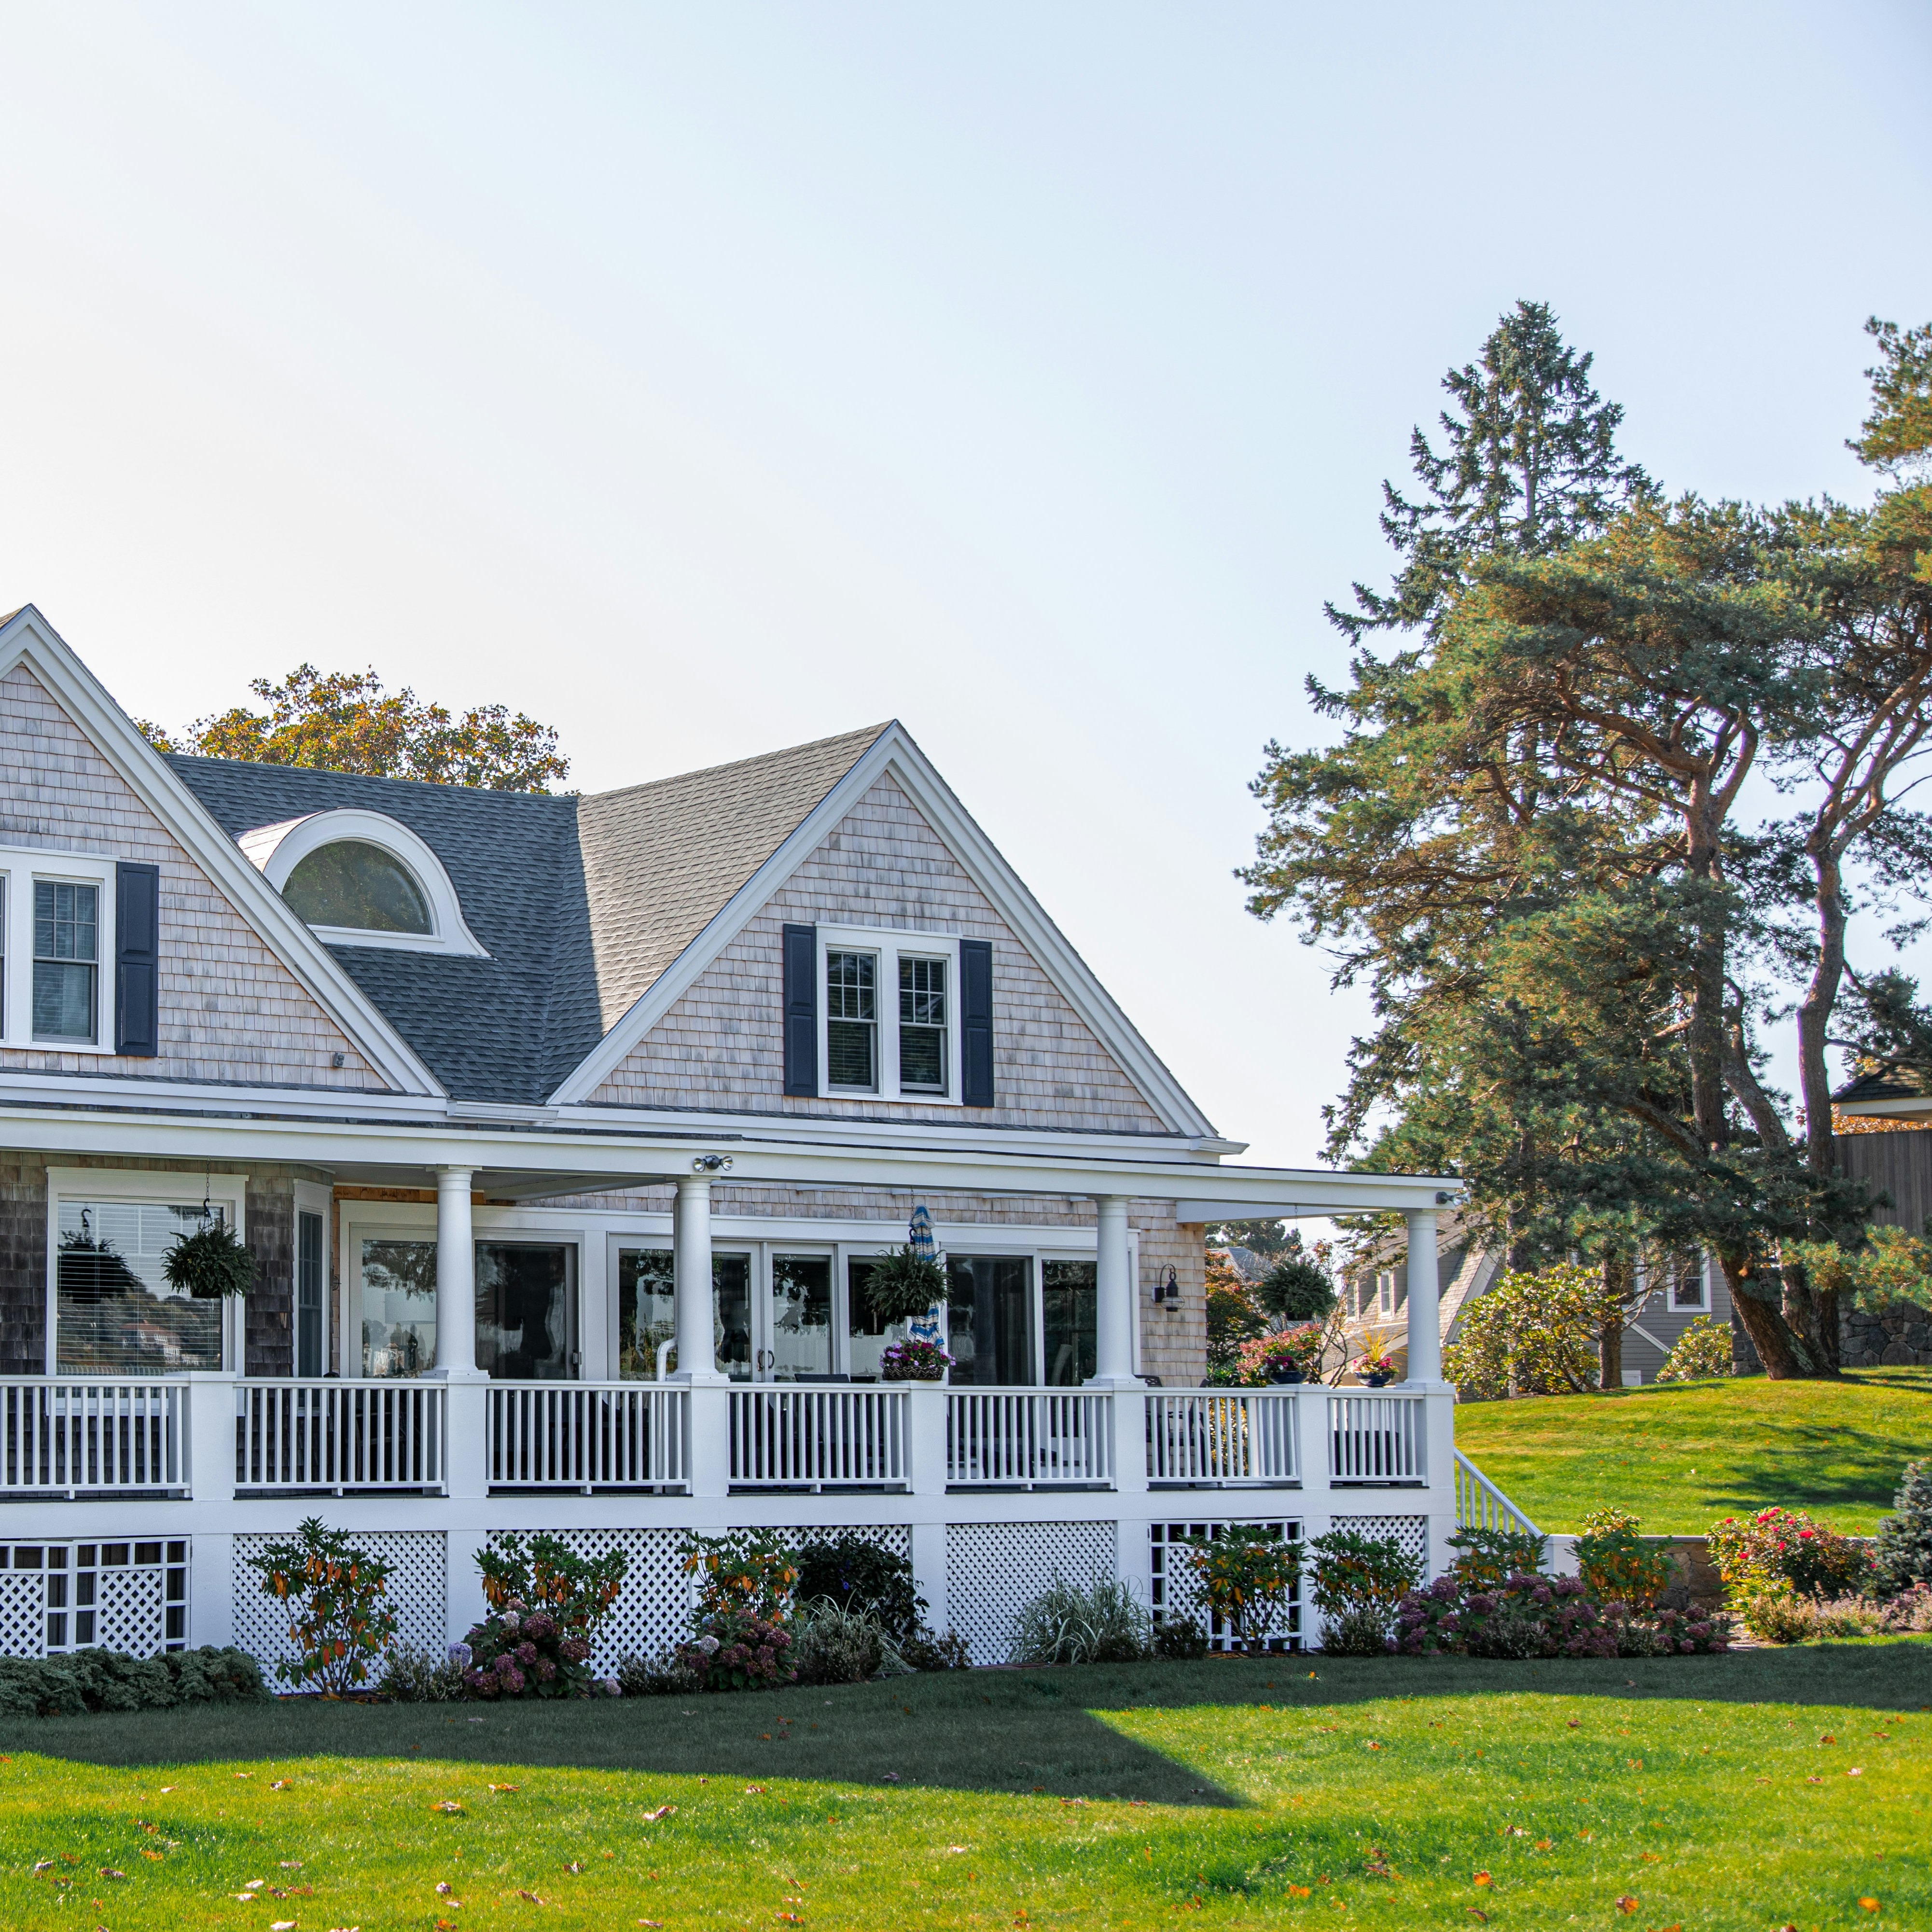
House in Coral Springs

Comparing Fee-Based Models With Traditional Brokers

Families in Coral Springs neighborhoods like Eagle Trace, Wyndham Lakes, and Running Brook Hills often wonder how fee-based financial planning differs from traditional commission-based brokerage services. Understanding these distinctions is important when choosing an advisor.

A fee-based financial advisor receives compensation primarily through direct client fees for advice and asset management, while disclosing any commissions from specialized insurance implementations transparently in writing. In contrast, traditional brokers often earn commissions based on product sales or transaction volume. The Financial Industry Regulatory Authority notes that fee transparency helps clients evaluate total advisory costs clearly.

Working with a fee-based fiduciary advisor confirms that guidance regarding 529 plans, 401(k) rollovers, and family insurance stays focused on your goals.
Growing families in Coral Springs

Addressing Hidden Planning Gaps In Household Budgets

Growing families in Coral Springs often encounter planning gaps as their earnings increase and household needs evolve. While many couples manage daily expenses well, they may overlook long-term structural items that impact financial security.

Common hidden planning gaps include: Inadequate Disability Coverage, relying solely on basic employer disability insurance that leaves bonus or commission income unprotected per US Bureau of Labor Statistics.; Unmatched Education and Retirement Goals, overfunding college savings accounts while underfunding retirement catch-up opportunities; and Outdated Estate Documents, lacking updated guardianship designations, wills, or healthcare powers of attorney for minor children.

Working with a personal trainer for money helps Coral Springs households address these gaps. Regular review checkups keep household plans balanced, ensuring that college funding, insurance coverage, and retirement accumulation move forward together smoothly.
RELATED READING

More From The Financial Planning Blog

Posts our planning team has put together on this topic.

Image for And the Executor Is

And the Executor Is

The right executor may help ensure the distribution of your assets is done with as little upheaval as possible.

Image for Financial Aid for Students 101

Financial Aid for Students 101

Help your college-bound child explore scholarships, grants, and more with this article on paying for higher education.
Image for FIRE Retirement

FIRE Retirement

This short, informative article teaches the basics of the FIRE movement.

Schedule Your Complimentary Consultation

No obligation. We respond the same business day.

I am Interested In
Approximate Household Income Range
Thank you! Your message has been received. Oops! Something went wrong. Please try again.

Questions, Answered

Frequently Asked Questions

Earlier than most households expect. Starting at 35 to 45 gives the plan runway on Social Security sequencing, Roth conversion windows, and tax-location decisions that compound over decades. The initial 30-minute discovery call is complimentary, and the engagement memo sizes scope and fee to your current balance sheet.

Three checks: (1) verify the CFP(R) mark at cfp.net under the planner's name, (2) read the firm's Form ADV Part 2A and confirm it says the firm acts as fiduciary at all times during advisory engagements, and (3) ask for a written fiduciary acknowledgment at the start of the engagement. All three should align before any plan deliverable is signed.

Three common structures: (1) a flat annual advisory fee covering the full plan, (2) a tiered percentage of assets under management for ongoing portfolio engagements, and (3) hourly rates for one-off project work. Our firm uses the first two primarily, with the specific rate written into the engagement memo. Compensation disclosures appear on Form ADV Part 2A.

The National Association of Personal Financial Advisors (NAPFA) directory lists fiduciary-only advisors. The CFP Board's search tool at cfp.net also lists compensation methods. Our firm is fee-based, not commission-free, with brokerage execution coordinated through J.W. Cole Financial and compensation sources disclosed on Form ADV Part 2A.

Retirement first, college second. The written plan maxes the 401(k) employer match (free money), then funds 529 plans to a target per child, then returns to retirement. For a Coral Springs dual-income household in the 24% to 32% federal bracket, the Florida 529 (no state deduction, but tax-free growth) typically funds in parallel with Backdoor Roth contributions.

The DB pension typically has a lump-sum option and an annuity option, with the lump-sum valuation set by current interest rates. We model both against your 401(k) rollover IRA, Social Security claim age, and spousal survivor needs. For most Coral Springs utility retirees, the annuity wins when the lump-sum interest rate is low; the lump-sum wins when rates are high.

Our Plantation office serves Coral Springs households. The office is at 7901 SW 6th Court, Suite 320, Plantation, FL 33324. From Coral Springs, the drive is about 20 minutes south on University Drive. We meet in person at the office or virtually through our secure client portal, Monday through Friday, 8:30 AM to 4:30 PM ET.

Yes. Every Coral Springs engagement supports both in-person and virtual meetings through our secure client portal. Document review, screen share, and plan sign-off all work remotely. Many clients mix the two, starting in person for the discovery call and running quarterly reviews over video.

Find Us

Plantation Office

Plantation

7901 SW 6th Court, Suite 320
Plantation, FL 33324
(954) 809-3553
Monday to Friday, 8:30 AM to 4:30 PM ET

Get Directions To The Office →

Neighborhoods We Serve In Coral Springs, FL

  • Eagle Trace
  • Country Club of Coral Springs
  • Heron Bay
  • Ramblewood
  • Oakwood
  • The Pines of Coral Ridge
  • Westchester
  • Royal Palm
  • Hidden Hammocks
  • Running Brook Hills
  • Shadow Wood
  • Pine Ridge
  • Mountain Lake Estates
  • Turtle Run
  • Whispering Woods
  • Cypress Run
  • Covered Bridge
  • Forest Hills
  • Maplewood Isles
  • Woodside Village
  • Dells
  • Riverside

Ready to talk about Financial Planning?

The first meeting is a conversation, not a sales pitch. We'll talk about where you are, what you're working through, and whether Intercoastal is the right fit. In person in Boca Raton or Plantation, or by video from anywhere.

Schedule A Consultation